Global oil giants are heading into a crucial earnings season with the prospect of significantly higher third-quarter profits, driven by disruptions linked to the US-Israeli war on Iran. But as companies prepare to report stronger results, investors are shifting their attention to a bigger question: will the unexpected cash windfall strengthen their finances, or encourage another costly spending cycle?
The conflict, which began in February, has severely disrupted shipping through the Strait of Hormuz, one of the world’s most important energy corridors. The resulting volatility has pushed energy prices to multi-year highs and created profitable opportunities for oil companies involved in refining, commodity trading and gas marketing.
For major energy producers, the situation presents both an opportunity and a test of financial discipline. The industry has experienced repeated boom-and-bust cycles, with periods of exceptional profits often followed by aggressive spending, rising debt and disappointing returns. This time, companies have pledged to maintain tighter control over costs and prioritise financial stability.
Refining profits surge as energy markets remain volatile
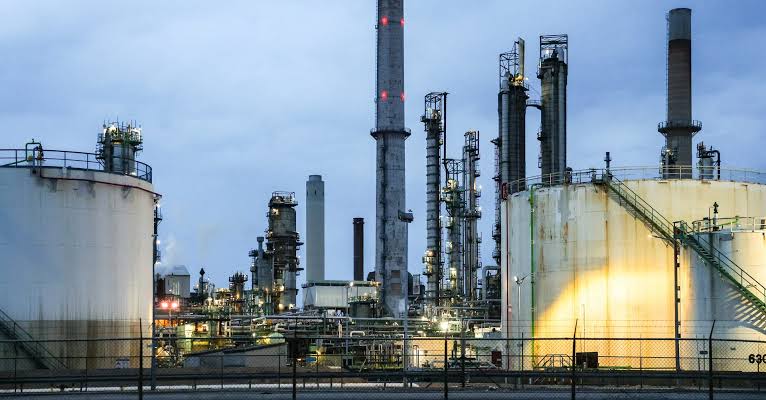
Shell, BP and TotalEnergies are expecting substantial improvements in refining margins during the third quarter compared with the same period last year. Their outlooks point to how sharply disruptions in global energy markets can influence the profitability of refining operations.
Shell has indicated that its refining margin could reach a record $42 per barrel. TotalEnergies expects cash flow from its refining and chemicals business to double to approximately $4 billion compared with the previous quarter.
ExxonMobil has also signalled that stronger refining margins could increase its downstream earnings by $4.5 billion compared with the second quarter.
These figures underline the financial advantages that major energy companies can gain during periods of market instability. However, the benefits are not necessarily permanent. Refining margins, commodity prices and trading opportunities can change quickly as supply routes reopen, demand shifts or geopolitical conditions evolve.
Investors question whether oil giants will increase spending
As third-quarter earnings announcements approach, investors are examining whether companies will maintain their existing investment plans or use their additional cash to pursue new projects and expand operations.
RBC Capital Markets analyst Biraj Borkhataria highlighted the importance of capital allocation during this period of exceptional earnings, noting that investors will be watching how companies manage their financial resources.
So far, Chevron and ExxonMobil have used some of their available cash to reduce debt, a move that could strengthen their balance sheets and provide greater resilience if oil prices fall.
Chevron’s investors are also expected to monitor the company’s investment plans in Venezuela and its progress towards extending its contract to operate the TCO joint venture in Kazakhstan. The venture is developing the country’s largest oilfield, making its future an important consideration for Chevron’s long-term production strategy.
Shareholder returns are another key issue. HSBC expects Shell to announce a share buyback worth $3.5 billion for the fourth quarter, following a reduction in its buyback programme to $3 billion per quarter earlier in the year.
The challenge for management teams is to balance shareholder expectations with the need to maintain investment, reduce debt and prepare for a less favourable market environment.
BP’s financial recovery gains momentum
BP is attracting particular attention following an encouraging trading update. Investment bank TPH has identified the British energy company as its preferred choice among European oil majors, citing the potential for stronger underlying earnings.
BP’s underlying profit could exceed $7 billion in the third quarter, compared with $5.7 billion in the previous quarter, supported by refining performance and gas marketing and trading activities.
The additional cash could accelerate BP’s efforts to repair its balance sheet after a period of financial pressure. Data cited by Citi suggests that BP’s net debt-to-operating-cash-flow ratio could decline from 1.7 times at the end of 2025 to an expected 0.8 times in the third quarter.
That improvement would represent a significant change in the company’s financial position. BP had the highest ratio among the five largest oil majors at the end of 2025, making debt reduction a central priority for management.
The company is also approaching its target for reducing net debt about a year earlier than planned, supported in part by its decision to pause share buybacks this year.
HSBC analysts Kim Fustier and Sadnan Ali expect BP to maintain its focus on reducing debt, with capital expenditure remaining stable and no resumption of share buybacks before 2028. BP has also indicated that it will provide a strategy update on December 15.
For investors, the company’s upcoming results will offer an important indication of whether its improving earnings can translate into a more sustainable financial position.
Earnings dates put capital allocation in focus
The upcoming reporting schedule will give investors an opportunity to compare how the major oil companies are responding to the same broad market conditions.
Shell and TotalEnergies are scheduled to report their third-quarter results on October 29, followed by BP, Chevron and ExxonMobil on October 30.
Beyond headline profits, investors are likely to focus on debt levels, capital expenditure, shareholder distributions and management’s expectations for the months ahead. Strong earnings may support share prices in the short term, but the longer-term outlook will depend on whether companies can turn temporary market advantages into lasting financial strength.
A windfall is valuable only if it builds lasting strength
The Iran war has created extraordinary opportunities for some of the world’s largest energy companies, but higher profits do not automatically guarantee a stronger future. A business can earn billions during a market disruption and still make poor decisions if it commits too much money to expensive projects or increases shareholder payouts without considering the next downturn.
For oil majors, this earnings season is about more than celebrating a surge in revenue. It is a test of whether years of promises about financial discipline will hold when cash is flowing freely.
Investors will be looking for evidence that companies are using this moment wisely: reducing debt, investing selectively, protecting balance sheets and rewarding shareholders without sacrificing resilience. In an industry where market conditions can change overnight, the strongest companies may not be those that earn the most during a windfall, but those that make the smartest decisions with it.